
The civic record
Read. Follow. Verify.Kentucky bill caps merchant processing early-termination fees and requires bold disclosure of agreement terms
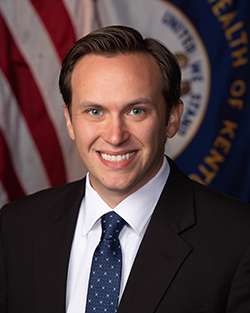
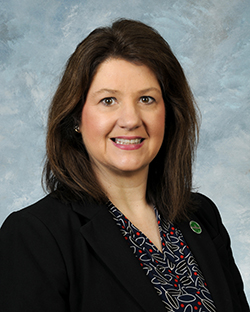
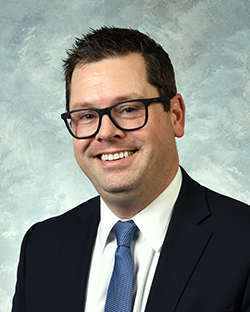
Last action · March 4, 2026: to Banking & Insurance (H)Sponsors: Nick Wilson and 2 others
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Kentucky House Bill 736 caps early-termination fees for credit card processing agreements at the greater of $500 or the unreimbursed cost of gifted or sold equipment, and prohibits penalties for declining to renew contracts. The measure requires processors to display termination terms, expiration dates, renewal dates, and customer service contacts in bold 12-point font on the signature page with required initials and immediate delivery of the contract copy. These rules apply to agreements entered on or after the effective date, while exempting businesses that process over $2,500,000 annually and employ more than 30 workers.
Local businesses entering into merchant processing contracts gain statutory protection from excessive cancellation fees and non-renewal penalties, while processors must alter contract formatting and disclosure practices for smaller commercial clients.
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Credit card processors
Processors must limit early termination fees, stop charging non-renewal penalties, format contract signature pages in bold 12-point font with mandatory initials, and provide immediate copies of agreements to covered businesses.
Businesses
Covered businesses receive fee caps on contract terminations, protection from non-renewal fines, enhanced written disclosures, and immediate access to their signed contract copies.
Key Facts
- A credit card processor is prohibited from charging a termination fee exceeding the greater of $500 or the unreimbursed cost of equipment or personal property gifted or sold under the agreement.
- Processors cannot assess fees or penalties against a business for failing or declining to renew an agreement or enter into a subsequent contract.
- Processors must disclose termination fees, expiration dates, renewal dates, and customer service contact details clearly and conspicuously in bold 12-point font on the signature page.
- Merchant processing agreements must contain the initials of the business signatory next to the required disclosures in addition to the signature.
Show all 8 facts
- A copy of the signed and initialed agreement must be provided to the business in electronic or paper format at the time the agreement is entered into.
- Agreement provisions violating the fee caps or disclosure rules are rendered void and unenforceable.
- The legislation exempts agreements that can be terminated without any fee or penalty, and agreements entered into by businesses generating over $2,500,000 in annual transactions and employing more than 30 employees.
- The Act applies to contracts entered on or after the effective date of the Act.
Frequently Asked Questions
What is the maximum early-termination fee a credit card processor can charge?
Are all businesses covered under this bill?
What information must appear on the signature page of the agreement?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
2 actions- Mar 4, 2026HouseCommitteeto Banking & Insurance (H)
- Feb 25, 2026HouseIntroducedintroduced in House to Committee on Committees (H)
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Connected Entities
Sources
apps.legislature.ky.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 65)
- Controversy40Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz25Current news / social attention level
Publisher tools