
The civic record
Read. Follow. Verify.West Virginia Bill Allows Large Non-Profit Retailers to Retain Sales Tax for Job Training Programs
Last action · February 16, 2026: To House FinanceSponsor: Bob Fehrenbacher
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
House Bill 5617 allows certified s with annual sales of at least $1 million to retain 75 percent of revenue collected after the first $1 million. The retained funds must be used to provide job training and placement services for individuals facing barriers to employment.
Qualifying retailers gain the ability to redirect a portion of state sales tax collections into local workforce development programs, provided they meet specific job placement quotas and reporting requirements.
- State legislative measures in West Virginia regarding taxation are introduced and referred to specialized committees such as the House Finance Committee for review. context
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Workforce training community centers
Certified retailers may retain 75 percent of sales tax collections above $1 million to fund job training programs, subject to mandatory placement quotas and reporting rules.
Persons with disabilities or other barriers to employment
Individuals receive individualized training and employment plans, job coaching, and post-employment support services funded by retained tax revenues.
West Virginia Department of Revenue
The department is responsible for certifying retailers, reviewing compliance, conducting revocation hearings, and proposing legislative rules.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
What retailers are eligible to apply for certification?
How much tax revenue can a certified organization retain?
What must certified organizations do with the retained funds after their first year?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
4 actions- Feb 16, 2026HouseCommitteeTo House Finance
- Feb 16, 2026HouseIntroducedIntroduced in House
- Feb 16, 2026HouseCommitteeTo Finance
- Feb 16, 2026HouseIntroducedFiled for introduction
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
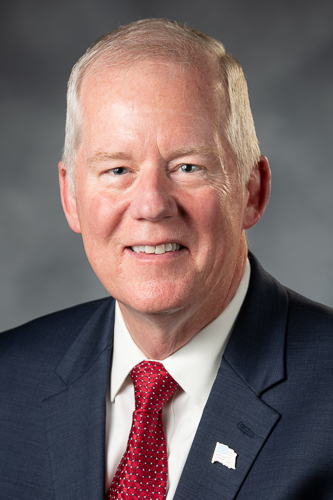
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Sales Tax Exemption Threshold Linked to Job Placement Quotas
The bill directly ties tax retention amounts to strict quantitative performance metrics, requiring 2.25 successful job placements per $10,000 retained after the initial year.
Connected Entities
Sources
www.wvlegislature.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 60)
- Controversy20Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz15Current news / social attention level
Publisher tools