
The civic record
Read. Follow. Verify.Louisiana Bill HB 212 Creates Delmont Economic Development District and Authorizes Local Taxes
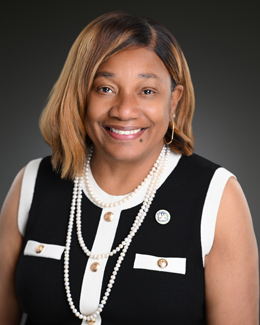
Last action · March 9, 2026: Read by title, under the rules, referred to the Committee on Municipal, Parochial and Cultural Affairs.Sponsor: Denise Marcelle
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Louisiana House Bill 212 creates the Delmont Economic Development District as a in East Baton Rouge Parish, empowering a seven-member board to fund local infrastructure, land acquisition, and revitalization projects. The measure authorizes the district to levy a sales and use tax of up to 1% and a hotel occupancy tax of up to 1%, both expiring after 20 years unless needed to pay off outstanding debt. Additionally, the district gains tax increment financing () authority and the ability to incur debt.
Property owners, business operators, and visitors within the newly defined Delmont area face potential new local taxes of up to 1% on retail sales and hotel room rentals. At the same time, the district gains broad legal powers to issue bonds, acquire property, and enter public-private partnerships aimed at local commercial revitalization.
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Residents within the Delmont Economic Development District
Residents face new sales taxes of up to 1% on retail purchases and potential neighborhood development activities.
Business owners and merchants in the district
Businesses are subject to district sales and use tax collection requirements and potential public-private economic initiatives.
Hotel operators within the district
Hotel operators must collect and remit a 1% hotel occupancy tax on room rentals.
Key Facts
- HB 212 enacts R.S. 33:9038.82 to establish the Delmont Economic Development District as a political subdivision in East Baton Rouge Parish.
- The district is governed by a seven-member board of commissioners appointed by local council members, the mayor-president, state legislators, and the Greater Baton Rouge Economic Partnership.
- Board members serve staggered four-year terms without compensation, except for reimbursement of reasonable out-of-pocket expenses.
- The district is authorized to levy and collect a sales and use tax of up to 1% within its territorial jurisdiction.
Show all 8 facts
- The district may levy and collect a hotel occupancy tax of up to 1% on rooms located within the district.
- Both the sales tax and hotel occupancy tax expire 20 years after initial levy, except that they continue if necessary to pay off principal and interest on outstanding bonds or debt.
- The district possesses tax increment finance (TIF) authority, including ad valorem TIF, sales tax TIF, and cooperative endeavor authority.
- The district has the power to sue and be sued, adopt bylaws, acquire and sell property, enter into contracts, and incur debt by issuing bonds or notes.
Frequently Asked Questions
What areas are included in the Delmont Economic Development District?
What new taxes can the district impose?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
4 actions- Mar 9, 2026HouseIntroducedRead by title, under the rules, referred to the Committee on Municipal, Parochial and Cultural Affairs.
- Feb 20, 2026HouseFirst appeared in the Interim Calendar on 2/20/2026.
- Feb 19, 2026HousePrefiled.
- Feb 19, 2026HouseCommitteeUnder the rules, provisionally referred to the Committee on Municipal, Parochial and Cultural Affairs.
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Creation of Specialized Local Taxing Authority
HB 212 establishes a new independent political subdivision equipped with both sales and hotel tax-levying powers alongside TIF authority within a specific urban neighborhood.
Connected Entities
Sources
www.legis.la.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 45)
- Controversy20Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz15Current news / social attention level
Publisher tools