
The civic record
Read. Follow. Verify.Kentucky Bill Allows Individual Income Tax Deductions for Theft Losses
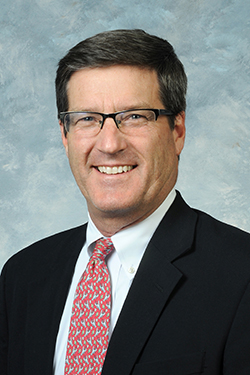
Last action · January 14, 2026: to Appropriations & Revenue (H)Sponsor: Ken Fleming
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Kentucky House Bill 167 permits individual taxpayers to deduct theft losses under Section 165(e) of the Internal Revenue Code when calculating for state tax purposes.
Individual taxpayers who experience theft losses can potentially lower their state taxable income by utilizing deductions previously excluded under state rules, altering how personal financial losses are reported on state tax returns.
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
individual taxpayers
Individual taxpayers are permitted to deduct theft losses when calculating their state net income.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
Does this bill allow me to deduct general financial losses on my state taxes?
Who does this tax law change apply to?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
2 actions- Jan 14, 2026HouseCommitteeto Appropriations & Revenue (H)
- Jan 7, 2026HouseIntroducedintroduced in House to Committee on Committees (H)
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Connected Entities
Sources
apps.legislature.ky.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 45)
- Controversy15Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz10Current news / social attention level
Publisher tools