
The civic record
Read. Follow. Verify.Senate Bill 830 Authorizes Small Loans by Deferred Presentment Providers and Establishes Consumer Regulations
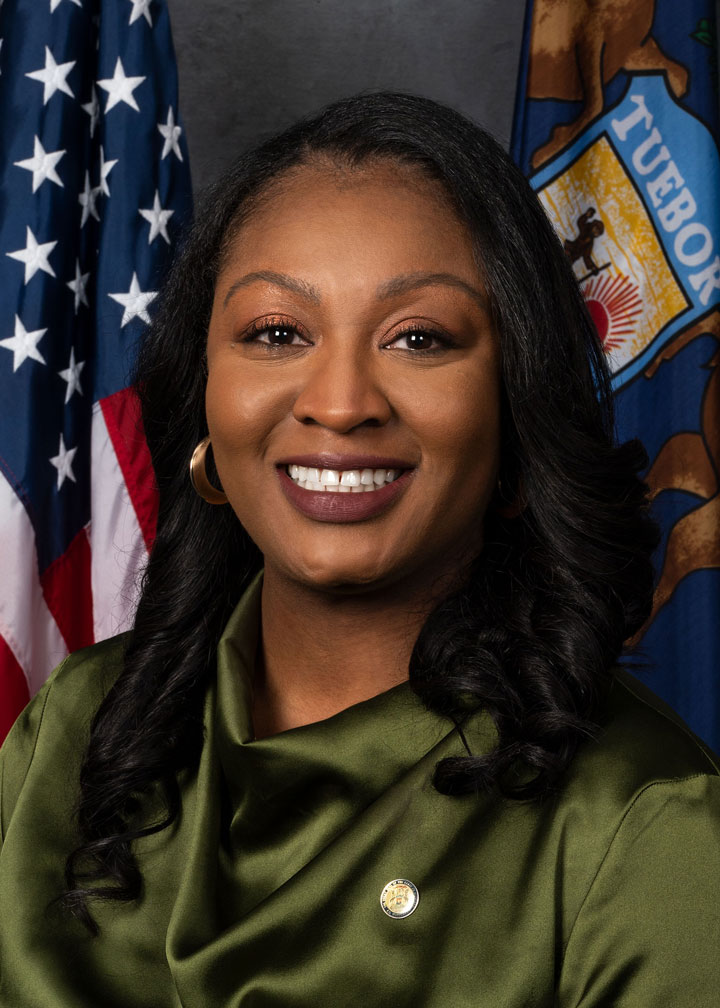
Last action · March 10, 2026: REFERRED TO COMMITTEE ON FINANCE, INSURANCE, AND CONSUMER PROTECTIONSponsor: Sarah Anthony
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Would Do
The bill would allow licensed providers of s (payday lenders) to make small unsecured loans up to $2,000 with terms between 90 and 365 days. It establishes strict underwriting requirements, including a debt-to-income ability-to-repay analysis, creates a consumer education and financial services access and literacy fund, and implements database tracking and expanded consumer complaint procedures.
The measure introduces a regulated framework for small-dollar installment loans up to $2,000 offered by payday lenders, establishing mandatory financial evaluations, interest rate caps up to 50%, credit reporting requirements, and restitution rules for affected consumers across the state.
Who It Would Affect
Groups the bill's text would affect if enacted, as described in the record. Being affected is not a position for or against it.
Consumers seeking small loans
Customers gain access to small installment loans up to $2,000.00 with mandatory ability-to-repay protections, cancellation rights, and credit reporting.
Licensed providers of deferred presentment service transactions
Licensees gain authorization to offer small installment loans, are subject to new underwriting and database reporting requirements, and face increased civil fines for violations.
Municipalities
Counties, townships, cities, and villages are eligible to apply for grants from the newly created financial literacy and education fund.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
What is the maximum amount and duration for a small loan under this bill?
Can a customer cancel a small loan agreement after signing it?
Are licensees allowed to charge prepayment penalties on small loans?
What are the rules regarding having multiple loans at the same time?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
Currently in committee. The next step in the legislative lifecycle is Floor Vote.
Procedural history
2 actions- Mar 10, 2026SenateCommitteeREFERRED TO COMMITTEE ON FINANCE, INSURANCE, AND CONSUMER PROTECTION
- Mar 10, 2026SenateIntroducedINTRODUCED BY SENATOR SARAH ANTHONY
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Connected Entities
Sources
legislature.mi.gov
Analysis Score
0–100- Significance75How much this matters to a regular citizen
- Controversy65Intensity of disagreement among stakeholders
- Entertainment10Compellingness for a non-policy-wonk reader
- Buzz40Current news / social attention level
Publisher tools