
The civic record
Read. Follow. Verify.Kentucky bill creates state income tax deduction for professional membership dues starting in 2027
Last action · March 3, 2026: to Appropriations & Revenue (H)Sponsors: Nima Kulkarni and 7 others
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Kentucky HB 725 allows individual taxpayers to deduct professional membership dues and fees from their state for taxable years beginning between January 1, 2027, and January 1, 2031. The measure applies to expenses required to maintain a professional license or association membership related to employment that are not deducted under federal tax law.
- Kentucky tax law defines adjusted gross income by starting with federal gross income and applying specific state-level additions and subtractions. context
- The Legislative Research Commission serves as the nonpartisan staff agency for the Kentucky General Assembly. context
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Licensed professionals
Individual taxpayers who pay mandatory professional association dues or license fees become eligible to claim a state income tax deduction starting in tax year 2027.
Department of Revenue
The department must track deduction claims and submit an annual report by November 1 to the Legislative Research Commission detailing usage and tax liability reductions.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
Who is eligible to claim the professional membership dues deduction?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
2 actions- Mar 3, 2026HouseCommitteeto Appropriations & Revenue (H)
- Feb 24, 2026HouseIntroducedintroduced in House to Committee on Committees (H)
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
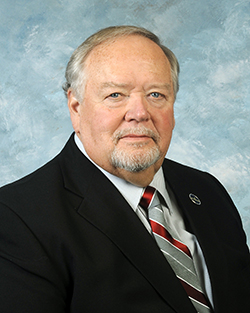
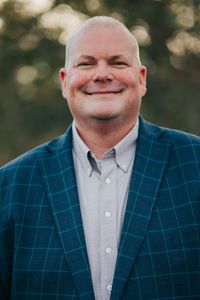
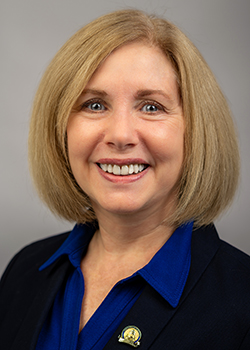
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Introduction of Professional Dues Deduction
The measure introduces a temporary four-year window (2027-2030) where professional membership dues not deducted federally can be subtracted from Kentucky adjusted gross income.
Connected Entities
Sources
apps.legislature.ky.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 55)
- Controversy15Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz25Current news / social attention level
Publisher tools