
The civic record
Read. Follow. Verify.West Virginia alters Build WV Act to cap tax credit liability, define rural areas, and establish reserve fund
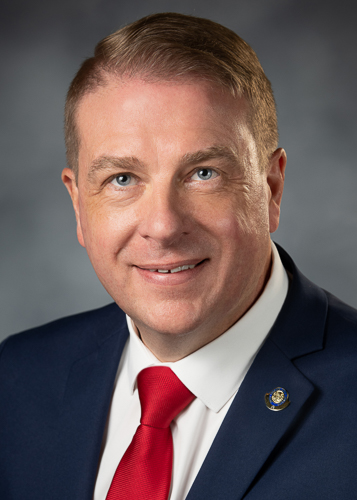
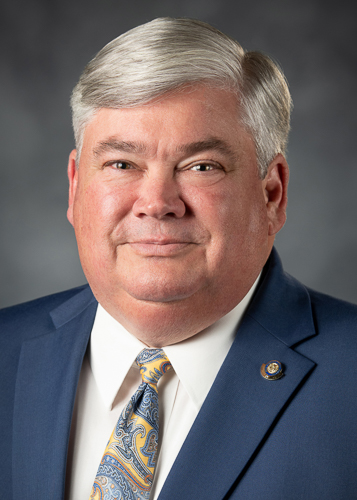
Last action · January 30, 2026: To FinanceSponsors: Vince Deeds and 1 other
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Senate Bill 627 modifies the Build WV Act by defining rural areas, replacing overall project cost caps with an annual $2 million limit on new tax credit liability, and lowering eligibility thresholds for smaller projects in rural areas. The measure also establishes an annually adjusted Build WV Credit Reserve Fund in the State Treasury and requires the Department of Economic Development to review program caps every five years.
Developers in designated rural areas may qualify for housing project tax credits with lower minimum costs and fewer residential units than standard projects, while state tax credit liabilities are capped at $2 million annually for new approvals.
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Eligible companies
Companies seeking certification for residential housing projects must comply with new rural definitions, project cost caps, and tax credit reservation limits.
Developers in rural areas
Rural developers may qualify for tax credits with lower cost thresholds and fewer housing units than standard statewide requirements.
Department of Economic Development
The department is required to evaluate project applications under revised standards, manage the new Credit Reserve Fund, and review fiscal caps every five years.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
What qualifies as a rural area under the amended Build WV Act?
Are smaller housing projects eligible if they are located in rural areas?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in Senate committee.
Procedural history
6 actions- Jan 30, 2026SenateCommitteeTo Finance
- Jan 30, 2026SenateCommittee substitute reported, but first to Finance
- Jan 27, 2026SenateCommitteeTo Economic Development
- Jan 27, 2026SenateIntroducedIntroduced in Senate
- Jan 26, 2026SenateCommitteeTo Economic Development then Finance
- Jan 26, 2026SenateIntroducedFiled for introduction
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Shift from Total Cost Caps to Annual Tax Credit Liability Caps
The legislation replaces a general project cost limitation framework with a specific $2 million annual cap on new property value adjustment tax credit approvals.
Connected Entities
Sources
www.wvlegislature.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 65)
- Controversy20Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz25Current news / social attention level
Publisher tools