
The civic record
Read. Follow. Verify.Kentucky House Bill 891 establishes monthly proration of motor vehicle property taxes for private party transfers
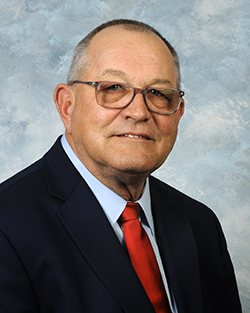
Last action · March 11, 2026: to Appropriations & Revenue (H)Sponsor: Richard White
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
House Bill 891 requires motor vehicle property taxes to be prorated on a monthly basis between private parties when a vehicle is transferred on or after January 1, 2027. Transfers occurring before the fifteenth of the month count toward the buyer's tax portion, while transfers on or after the fifteenth count toward the seller's portion. The bill also mandates automatic refunds for any overpayments created by these requirements without requiring a written request.
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
private party vehicle buyers
Buyers become liable for motor vehicle property taxes for the months following a vehicle transfer based on the specific day of the month the sale occurs.
private party vehicle sellers
Sellers remain liable for motor vehicle property taxes for the months they owned the vehicle up to the transfer date.
Key Facts
- Ad valorem taxes on motor vehicles transferred between private parties must be prorated on a monthly basis between the transferor and transferee.
- If a vehicle transfer occurs before the fifteenth day of a month, that month counts toward the transferee's tax portion.
- If a transfer occurs on or after the fifteenth day of a month, that month counts toward the transferor's tax portion.
- Overpayments resulting from the proration requirements must be refunded automatically without a written request from the taxpayer.
Show all 5 facts
- The provisions of this Act apply to motor vehicle transfers that occur on or after January 1, 2027.
Frequently Asked Questions
How is the tax month split if I sell my car mid-month?
Do I need to submit a written request to get a refund for a tax overpayment caused by proration?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
2 actions- Mar 11, 2026HouseCommitteeto Appropriations & Revenue (H)
- Mar 4, 2026HouseIntroducedintroduced in House to Committee on Committees (H)
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Connected Entities
Sources
apps.legislature.ky.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 60)
- Controversy15Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz20Current news / social attention level
Publisher tools