POLISCOPE
Back to bills

The civic record

Read. Follow. Verify.

Missouri Senate Bill 1575 allows resident estates and trusts to subtract capital gains from taxable income starting in 2026

Original title: Modifies provisions relating to capital gains taxes

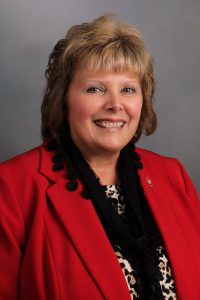
Last action · April 29, 2026: SCS Voted Do Pass S Economic and Workforce Development Committee (6743S.04C)Sponsor: Sandy Crawford

Introduced
Committee
Floor Vote
Passed
Law

Track this bill to get notified when it advances a stage. One tap to stop, anytime.

What This Bill Would Do

Resident estates and trusts in Missouri are permitted to subtract 100 percent of income reported as a capital gain for federal income tax purposes from their Missouri taxable income, beginning with tax years on or after January 1, 2026.

Why it matters

Changes state income tax calculations for resident estates and trusts by exempting capital gains from taxation, directly affecting the total tax liability owed to the state starting in the 2026 tax year.

Background
  • Current Missouri law authorizes an income tax deduction for a portion of income reported as a capital gain for federal income tax purposes. context

Who It Would Affect

Groups the bill's text would affect if enacted, as described in the record. Being affected is not a position for or against it.

Directly affected

Resident estates and trusts

Resident estates and trusts are permitted to subtract 100 percent of income reported as a capital gain for federal income tax purposes from their Missouri taxable income starting in 2026.

Key Facts

You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.

Frequently Asked Questions

Who is eligible for the capital gains tax subtraction under SB 1575?
Resident estates and trusts are eligible for the subtraction for tax years beginning on or after January 1, 2026.
What percentage of capital gains can be subtracted?
One hundred percent of all income reported as a capital gain for federal income tax purposes can be subtracted, provided it is not a determinant of federal .

What else do you want to know?

News Coverage

No news coverage found yet. Articles are indexed twice daily.

Where This Stands

Currently in committee. The next step in the legislative lifecycle is Floor Vote.

Procedural history

4 actions
  1. Apr 29, 2026SenateCommittee
    SCS Voted Do Pass S Economic and Workforce Development Committee (6743S.04C)
  2. Mar 11, 2026Senate
    Hearing Conducted S Economic and Workforce Development Committee
  3. Feb 5, 2026SenateFloor
    Second Read and Referred S Economic and Workforce Development Committee
  4. Jan 20, 2026SenateIntroduced
    S First Read

Version history & redline

2 versions on file
Comparing 6743S.02I - Introduced → Senate Committee Substitute - Committee Version
removed addedOfficial text
removed: EXPLANATION-Matter enclosed in bold-faced brackets [thus] in this bill is not enacted and is intended to be omitted in the law. SECOND REGULAR SESSION added: 6743S.04C 1 SENATE added: COMMITTEE SUBSTITUTE FOR SENATE BILL NO. 1575 removed: 103RD GENERAL ASSEMBLY INTRODUCED BY SENATOR CRAWFORD. 6743S.02I KRISTINA MARTIN, Secretary AN ACT To repeal removed: sections 143.121 and added: section 143.341, RSMo, and to enact in lieu thereof removed: two added: one new removed: sections added: section relating to capital gains taxes. Be it enacted by the General Assembly of the State of Missouri, as follows: Section A. removed: Sections 143.121 and added: Section 143.341, RSMo, removed: are added: is repealed and removed: two added: one new removed: sections added: section enacted in lieu thereof, to be known as removed: sections 143.121 and added: section 143.341, to read as follows: removed: 143.121. 1. The Missouri adjusted gross income of a resident individual shall be the taxpayer's federal adjusted gross income subject to the modifications in this section. 2. There shall be added to the taxpayer's federal adjusted gross income: (1) The amount of any federal income tax refund received for a prior year which resulted in a Missouri income tax benefit. The amount added pursuant to this subdivision shall not include any amount of a federal income tax refund attributable to a tax credit reducing a taxpayer's federal tax liability pursuant to Public Law 116- 136 or 116-260, enacted by the 116th United States Congress, for the tax year beginning on or after January 1, 2020, and ending on or before December 31, 2020, and deducted from Missouri adjusted gross income pursuant to section 143.171. The amount added under this subdivision shall also not include any amount of a federal income tax refund attributable to a tax credit reducing a taxpayer's federal tax liability under any other federal law that provides direct economic impact payments to taxpayers to mitigate financial challenges related to the COVID-19 pandemic, and deducted from Missouri adjusted gross income under section 143.171; (2) Interest on certain governmental obligations excluded from federal gross income by 26 U.S.C. Section 103 of the Internal Revenue Code, as amended. The previous sentence shall not apply to interest on obligations of the state of Missouri or any of its political subdivisions or authorities and shall not apply to the interest described in subdivision (1) of subsection 3 of this section. The amount added pursuant to this subdivision shall be reduced by the amounts applicable to such interest that would have been deductible in computing the taxable income of the taxpayer except only for the application of 26 U.S.C. Section 265 of the Internal Revenue Code, as amended. The reduction shall only be made if it is at least five hundred dollars; (3) The amount of any deduction 18,406 more removed characters - read the previous version143.341. 1. The Missouri taxable income of a resident estate or trust means its federal taxable income subject to the modifications in this section. […] shall be subtracted the federal income tax deduction provided in section 143.171. These additions and subtractions shall only apply to the extent that they added: 2 are not determinants of the federal distributable net income of the estate or trust. 5. There shall be added or subtracted, as the case […] the estate or trust in the fiduciary adjustment determined under section 143.351. 6. For all tax years beginning on or after January 1, 2026, added: to the extent included in federal adjusted gross income, there shall be subtracted one hundred percent of all income reported as a capital gain for federal income tax purposes. removed: 7. For all tax years beginning on or after January 1, 2026, a capital gain added: This subtraction shall removed: include items added: only apply to the extent that they are not determinants of removed: ordinary income for added: the federal added: distributable net income removed: tax purposes that, but for the application of removed: 26 U.S.C. Sections 1245 and 1250 of the removed: Internal Revenue Code, as amended, would be treated as a capital gain.added: estate or trust.
Redline computed from the official version text (record lane).View this version →

Lobbying Activity

No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.

Full breakdown

Who this bill affects and the strongest case for and against it, written only from the bill’s own text.

Sponsors
Discoveries

1 pattern noticed across the record

Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.

policy shift95% confidence

Extension of Capital Gains Treatment to Estates and Trusts

The bill expands existing capital gains tax relief mechanisms to include resident estates and trusts starting in 2026.

Connected Entities

General Assembly, Sandy Crawford
OrganizationGeneral Assembly“The legislative body enacting the bill.”Map →
PersonSandy Crawford“Primary sponsor of Senate Bill 1575.”Map →

Sources

Open source document

www.senate.mo.gov

Analysis Score

0–100
  • Significance60
    How much this matters to a regular citizen
  • Controversy15
    Intensity of disagreement among stakeholders
  • Entertainment5
    Compellingness for a non-policy-wonk reader
  • Buzz25
    Current news / social attention level

Publisher tools

Share or embed this record

POLISCOPE publisher tools

Share or embed this record