
The civic record
Read. Follow. Verify.Kentucky Bill 101 exempts religious institutions from state sales and use taxes
Last action · February 9, 2026: floor amendments (1) and (2-title) filedSponsors: James Tipton and 52 others
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Kentucky HB 101 exempts religious institutions and their single-member limited liability companies from state es on purchases and sales used solely within their religious functions. The measure separates the definition of religious institutions from educational and charitable institutions in state tax code.
- The Kentucky General Assembly is the state legislature responsible for enacting and amending state tax statutes. context
- Section 501(c)(3) of the Internal Revenue Code governs federal tax-exempt status for religious, educational, and charitable organizations. context
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
religious institutions
Religious institutions gain explicit sales and use tax exemptions for purchases and sales used solely within their religious function.
educational or charitable institutions
Educational and charitable institutions are separated from religious institutions in the tax code definitions and retain existing specific exemptions and refund provisions.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
What organizations qualify as a religious institution under this bill?
Are all sales by religious institutions exempt from tax?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · on the House floor.
Procedural history
3 actions- Feb 9, 2026Housefloor amendments (1) and (2-title) filed
- Jan 14, 2026HouseCommitteeto Appropriations & Revenue (H)
- Jan 7, 2026HouseIntroducedintroduced in House to Committee on Committees (H)
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
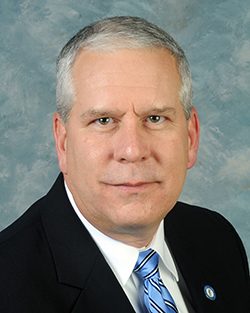
Show 48 more sponsors
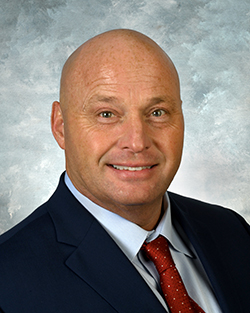

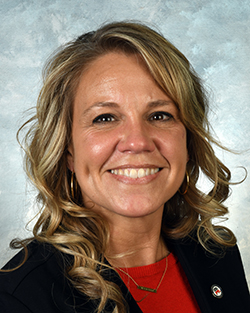
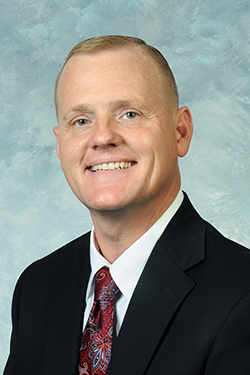














Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Decoupling of Religious and Charitable Tax Definitions
The bill formally separates religious institutions from educational and charitable institutions within Kentucky's sales and use tax statutes.
Connected Entities
Sources
apps.legislature.ky.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 65)
- Controversy40Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz30Current news / social attention level
Publisher tools