
The civic record
Read. Follow. Verify.West Virginia creates state tax credit for biochar manufacturing facilities tied to federal carbon…
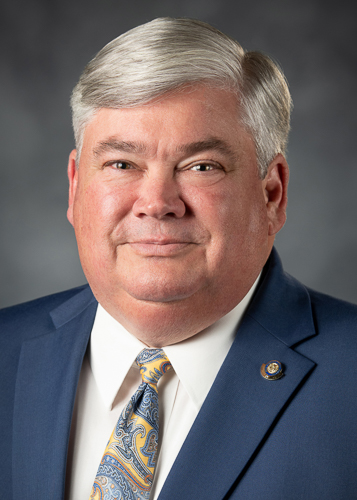
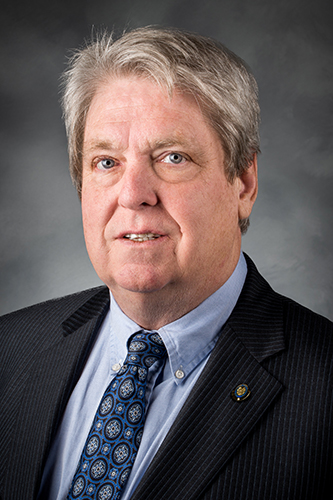
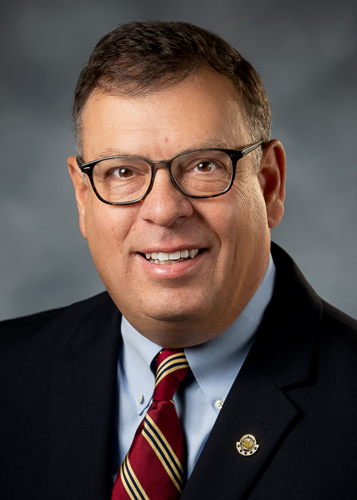
Last action · February 24, 2026: To FinanceSponsors: Glenn Jeffries and 6 others
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
West Virginia establishes a state corporate net income tax credit equal to 10 percent of the federal Section 45Q tax credit for eligible taxpayers operating qualified manufacturing facilities in the state starting July 1, 2026. The credit is capped at 50 percent of the taxpayer's annual tax liability before credits, allows carrybacks and carryforwards under federal rules, and can be claimed for up to 12 years.
Qualifying advanced manufacturing facilities operating in West Virginia can reduce their state corporate income tax liability by up to 10 percent of their federal carbon sequestration credits, impacting state tax revenues and providing financial incentives for forestry and industrial residue processing businesses.
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
eligible taxpayers
Corporations and pass-through entities owning qualified biochar facilities become eligible to claim a state tax credit against corporate net income tax liability.
shareholders, partners, and members of pass-through entities
Owners of electing small business corporations, partnerships, and LLCs receive flow-through tax credits allocated in the same manner as profits and losses.
West Virginia State Tax Department
The department is responsible for receiving documentation, verifying compliance, relying on IRS certifications, and promulgating rules to administer the tax credit.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
What businesses qualify for the new West Virginia tax credit?
How much is the state tax credit worth?
How long can a facility claim the state tax credit?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in Senate committee.
Procedural history
6 actions- Feb 24, 2026SenateCommitteeTo Finance
- Feb 24, 2026SenateCommitteeReported do pass, but first to Finance
- Feb 10, 2026SenateCommitteeTo Economic Development
- Feb 10, 2026SenateIntroducedIntroduced in Senate
- Feb 10, 2026SenateCommitteeTo Economic Development then Finance
- Feb 10, 2026SenateIntroducedFiled for introduction
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Alignment with Federal 45Q Tax Credits
The bill explicitly ties state tax policy to federal 26 U.S.C. § 45Q carbon sequestration credits, delegating eligibility determinations entirely to the Internal Revenue Service.
Connected Entities
Sources
www.wvlegislature.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 60)
- Controversy15Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz25Current news / social attention level
Publisher tools