
The civic record
Read. Follow. Verify.Kentucky Replaces Board of Tax Appeals with Executive Branch Tax Tribunal
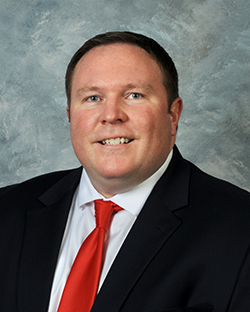
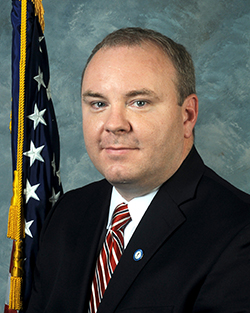
Last action · February 23, 2026: to Appropriations & Revenue (H)Sponsors: Patrick Flannery and 1 other
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Kentucky HB 645 abolishes the Kentucky Board of Tax Appeals and establishes the independent Kentucky Tax Tribunal within the executive branch effective January 1, 2028, granting it exclusive statewide jurisdiction over state and local tax disputes. The measure divests Circuit and District Courts of original jurisdiction over civil tax matters and sets new procedures, filing fees, and judicial review standards for taxpayers.
Taxpayers and local governments face a completely restructured dispute-resolution framework, shifting original tax appeals away from local courts into a specialized Frankfort tribunal with mandatory filing fees ranging from $100 to $500 ($25 for small claims).
- Specialized tax tribunals and courts operate in over 35 states, providing dedicated forums outside traditional general jurisdiction courts to resolve tax disputes. context
- The Kentucky Board of Tax Appeals previously served as the primary administrative review body for tax disputes in the Commonwealth before its planned abolition under this act. context
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Taxpayers
Taxpayers must file petitions within 30 days of receiving a final taxing agency ruling, pay set filing fees, and present cases before the new tribunal instead of local Circuit or District Courts.
Local Governments
Local taxing agencies and authorities are subject to the tribunal's exclusive jurisdiction for local tax disputes and must answer petitions within specified timeframes.
Legal Practitioners
Attorneys representing taxpayers must adhere to new tribunal rules, representation requirements, and pro hac vice fee structures.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
Do I have to pay my tax assessment before appealing to the tribunal?
What are the filing fees for bringing a case to the tribunal?
Where can I appeal a decision made by the Kentucky Tax Tribunal?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in House committee.
Procedural history
2 actions- Feb 23, 2026HouseCommitteeto Appropriations & Revenue (H)
- Feb 13, 2026HouseIntroducedintroduced in House to Committee on Committees (H)
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Centralization of Tax Dispute Adjudication
The General Assembly is shifting original jurisdiction over civil tax matters away from local Circuit and District Courts into a newly created specialized executive-branch tribunal in Frankfort.
Connected Entities
Sources
apps.legislature.ky.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 85)
- Controversy40Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz30Current news / social attention level
Publisher tools