
The civic record
Read. Follow. Verify.West Virginia Senate Bill 702 sets maximum interest rates and fee rules for consumer lenders
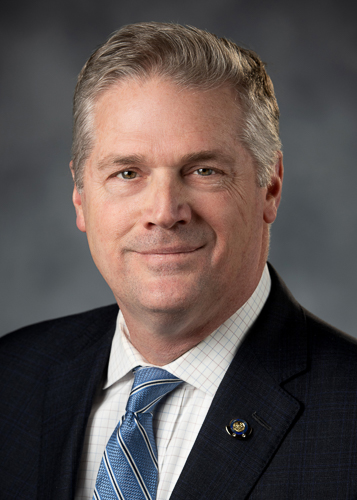
Last action · February 12, 2026: To FinanceSponsor: Mike Azinger
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Proposed
Senate Bill 702 establishes new maximum annual interest rates for regulated consumer lenders on installment loans up to $35,000 and removes a prior cap on s when calculating finance charges. The measure sets specific interest rate caps ranging from 18 percent to 36 percent depending on the loan amount and whether it is secured by real property. It also updates rules regarding allowable origination fees, points, and investigation fees.
- Senate Bill 702 was introduced during the 2026 Regular Session of the West Virginia Legislature by Senator Azinger and referred to committee. context
- Regulated consumer lenders in West Virginia operate under statutory limits governing loan finance charges, origination fees, and repayment terms as codified in Chapter 46A of the West Virginia Code. context
Who It Would Have Affected
Groups the bill's text would have affected, as described in the record. Being affected is not a position for or against it.
Regulated consumer lenders
Lenders must comply with revised maximum annual interest rate caps and updated limits on origination, point, and investigation fees for installment loans.
Consumers obtaining installment loans up to $35,000
Borrowers are subject to new statutory interest rate maximums and fee structures on consumer loans up to $35,000.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
What is the maximum interest rate a regulated consumer lender can charge on an installment loan under this bill?
Are lenders allowed to charge origination fees or points on these loans?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
This bill did not become law - Died at adjournment · in Senate committee.
Procedural history
6 actions- Feb 12, 2026SenateCommitteeTo Finance
- Feb 12, 2026SenateCommitteeReported do pass, but first to Finance
- Feb 2, 2026SenateCommitteeTo Banking and Insurance
- Feb 2, 2026SenateIntroducedIntroduced in Senate
- Feb 2, 2026SenateCommitteeTo Banking and Insurance then Finance
- Feb 2, 2026SenateIntroducedFiled for introduction
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Connected Entities
Sources
www.wvlegislature.gov
Analysis Score
0–100- Significance20Lowered because this bill did not pass (its text scored 75)
- Controversy50Intensity of disagreement among stakeholders
- Entertainment10Compellingness for a non-policy-wonk reader
- Buzz25Current news / social attention level
Publisher tools