
The civic record
Read. Follow. Verify.Michigan SB 417 earmarks corporate income tax revenue for the beverage container handling fund starting in fiscal year 2026-2027
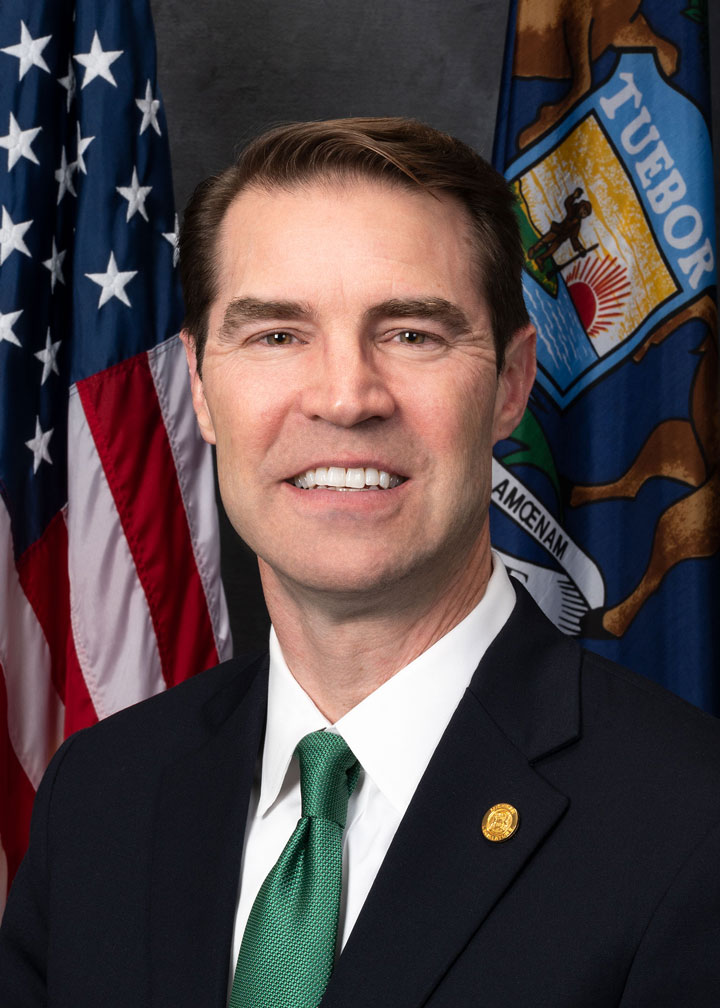
Last action · June 12, 2025: REFERRED TO COMMITTEE ON ENERGY AND ENVIRONMENTSponsor: Sean McCann
Track this bill to get notified when it advances a stage. One tap to stop, anytime.
What This Bill Would Do
Michigan Senate Bill 417 alters the distribution of corporate income tax revenue beginning in the 2026-2027 state by directing $60,000,000.00 annually to the beverage container handling fund after housing fund allocations. The measure is contingent upon the enactment and voter approval of Senate Bill No. 416 at the November 3, 2026 general election.
The change alters how state corporate tax dollars are divided, establishing a dedicated annual revenue stream for beverage container handling and housing funds starting in 2026-2027. It requires voter approval of a companion bill before taking effect.
- Corporate income tax collections in Michigan are deposited into the general fund by default unless specifically earmarked by statute for particular funds. context
- Senate Bill 417 was introduced in the Michigan Senate and referred to the Committee on Energy and Environment during the 2025-2026 legislative session. context
Who It Would Affect
Groups the bill's text would affect if enacted, as described in the record. Being affected is not a position for or against it.
Michigan taxpayers
Corporate income tax revenues paid by taxpayers are redistributed to specific state funds rather than entirely to the general fund.
State general fund
Receives the remaining balance of corporate income tax collections after specific statutory fund allocations are deducted.
Key Facts
You don't have to trust us. Each fact below is taken straight from the official document - click any one to see the exact passage, highlighted in the original.
Frequently Asked Questions
Where does corporate income tax revenue go under this bill for the 2025-2026 fiscal year?
How is the allocation for the beverage container handling fund calculated after 2026-2027?
What must happen for this bill to take effect?
What else do you want to know?
News Coverage
Follow the record
Votes, people, money & the original sourceWhere This Stands
Currently in committee. The next step in the legislative lifecycle is Floor Vote.
Procedural history
2 actions- Jun 12, 2025SenateCommitteeREFERRED TO COMMITTEE ON ENERGY AND ENVIRONMENT
- Jun 12, 2025SenateIntroducedINTRODUCED BY SENATOR SEAN MCCANN
Version history
Only one version on file - nothing to compare yet. As later stages (committee substitute, engrossed, enrolled) are captured, the redline appears here.
View official text →Lobbying Activity
No state lobbying filings in our records match this bill. Federal lobbying reports (LDA) cover Congress, so they are not listed on state bills.
Full breakdown
Who this bill affects and the strongest case for and against it, written only from the bill’s own text.
Sponsors
Discoveries
Patterns POLISCOPE noticed across the record. These are observations to investigate, not conclusions.
Creation of Dedicated Container Fund Revenue
The bill introduces a permanent, inflation-adjusted annual allocation of $60,000,000.00 from corporate income taxes to the beverage container handling fund starting in 2026-2027.
Connected Entities
Sources
legislature.mi.gov
Analysis Score
0–100- Significance50How much this matters to a regular citizen
- Controversy25Intensity of disagreement among stakeholders
- Entertainment5Compellingness for a non-policy-wonk reader
- Buzz20Current news / social attention level
Publisher tools